QSBS (Qualified Small Business Stock) is a federal tax provision under Section 1202 of the Internal Revenue Code that lets you exclude up to millions of dollars in capital gains when you sell stock in a qualifying small business.
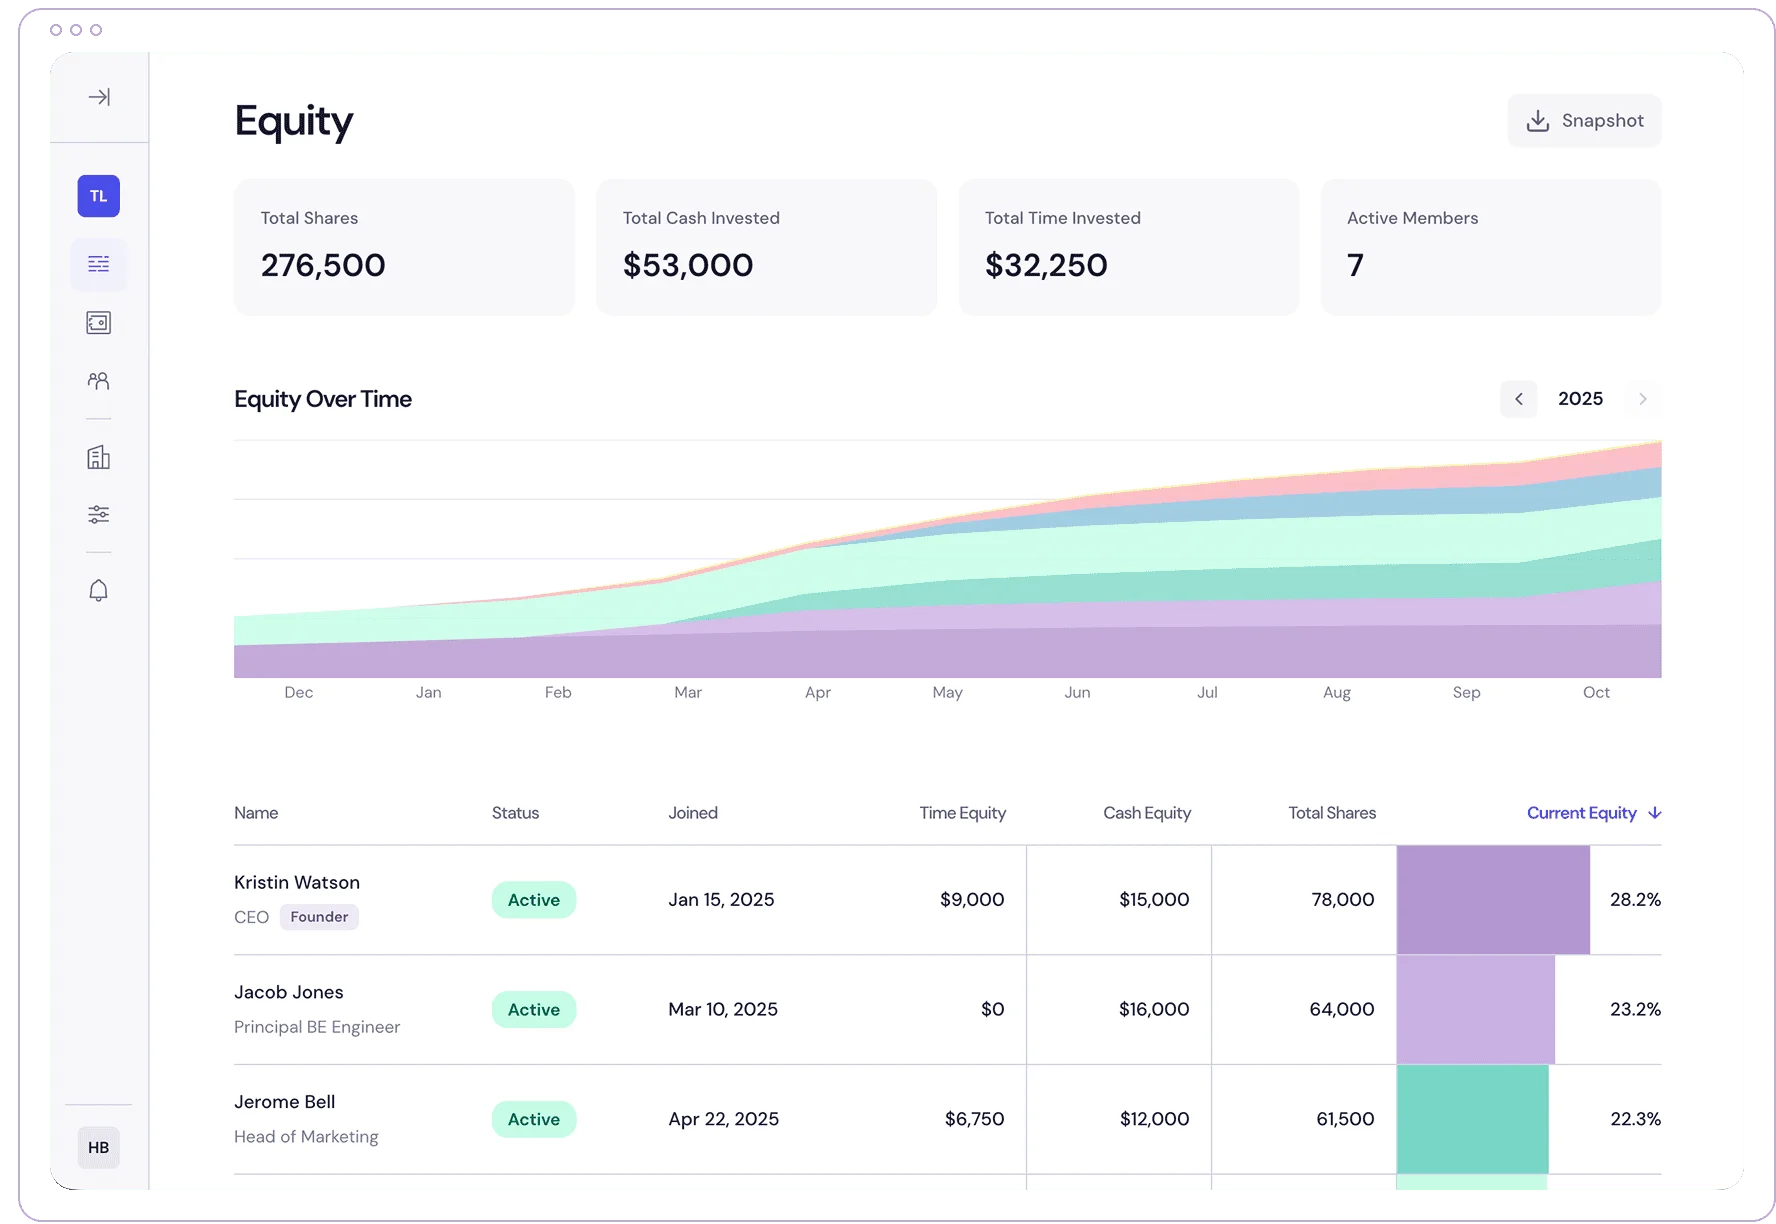
If you’re a founder holding C-corp equity, QSBS is one of the most powerful tax benefits available to you. And for qualifying stock acquired after July 4, 2025, it got significantly better. The equity calculator can help you model what your ownership percentage looks like at exit so you know how much of the applicable exclusion actually applies to your stake.
The One Big Beautiful Bill Act, signed into law last summer, created a new regime for QSBS acquired after July 4, 2025. Stock acquired on or before that date stays under the old regime: a five-year hold, a $10 million or 10-times-basis cap, and a $50 million gross-assets ceiling.
Here’s what changed, who qualifies, and what you should do about it.
What Changed in the One Big Beautiful Bill Act
The OBBBA made three meaningful updates to Section 1202 for stock acquired after July 4, 2025. Each one independently makes QSBS more accessible. Together, they represent the biggest upgrade to startup tax benefits in over a decade.
1. Holding Period: 5 Years to 3 Years (Tiered)
Previously, you had to hold your qualifying stock for at least five years before you could exclude any gains. That’s a long time in the startup world.
Now, the holding period is tiered:
| Holding Period | Exclusion |
|---|---|
| 3 years | 50% of gains excluded |
| 4 years | 75% of gains excluded |
| 5+ years | 100% of gains excluded |
This is a big deal. If your startup gets acquired at year three, you’re no longer shut out entirely. You still get half the exclusion. At four years, you get 75%. And the full 100% exclusion now kicks in at five years, same as before, but the tiered structure means even earlier exits have meaningful tax benefits.
2. Asset Threshold: $50M to $75M
To qualify under the new regime, your company’s aggregate gross assets must not exceed $75 million both before and immediately after the stock is issued. Stock acquired on or before July 4, 2025 remains subject to the old $50 million ceiling.
This matters because many startups that raise a Series B or C were bumping up against the old limit. A company with $60M in gross assets after a fundraise would have disqualified new stock issuances entirely. Now there’s more room.
3. Gain Exclusion Cap: $10M to $15M (With Inflation Indexing)
For stock acquired after July 4, 2025, the per-taxpayer, per-issuer dollar cap is $15 million, while the alternative cap of 10 times basis still applies; the greater limit controls. Earlier stock retains the old $10 million or 10-times-basis limit.
The new $15 million cap and $75 million gross-assets ceiling are indexed beginning with tax years after 2026, so the first adjustment is in 2027 using 2025 as the base year. Specific 2027 amounts are not available yet, and Treasury guidance on the OBBBA Section 1202 changes remains pending as of September 2026.
Who Qualifies for QSBS
The core requirements haven’t changed. Your stock must meet all of these:
- C-corporation. The company must be a C-corp at the time the stock is issued. LLCs, S-corps, and partnerships don’t qualify. If you’re currently structured as an LLC, this is worth a conversation with your attorney.
- Applicable gross-assets test. For post-July 4, 2025 stock, the company’s aggregate gross assets must not exceed $75 million both before and immediately after issuance; the ceiling is $50 million for earlier stock. The test generally uses adjusted tax basis, but contributed property is counted at fair market value.
- Active business requirement. At least 80% of the company’s assets must be used in an active trade or business. Certain industries are excluded: hospitality, banking, farming, mining, and professional services like law and accounting.
- Applicable holding period. Post-July 4, 2025 stock gets a 50% exclusion at three years, 75% at four years, and 100% at five years. Earlier stock receives no exclusion before five years and remains under the old regime.
- Original issuance. You must have acquired the stock directly from the company (at incorporation, through an option exercise, or similar). Stock purchased on the secondary market generally doesn’t qualify.
83(b) Elections Explained: Filing Early Is Even More Important Now
If you filed an 83(b) election when you received your shares, your holding period starts from the grant date. If you didn’t, it starts from the vesting date. With partial exclusions now available at three and four years for post-July 4, 2025 stock, filing your 83(b) on time is more important than ever.
Why This Matters for Founders
Let’s make this concrete.
Say you founded a C-corp, received stock at incorporation worth essentially nothing, and four years later the company gets acquired. Your shares are worth $12 million at exit.
Old regime: At four years, none of the $12 million gain is excluded. Any tax estimate depends on the taxpayer’s full return, including the applicable capital-gains rate and potential 3.8% net investment income tax (NIIT).
New regime: If the stock was acquired after July 4, 2025, four years produces a 75% exclusion: an estimated $9 million of a $12 million gain is excluded and $3 million remains subject to the special federal rate rules for partially excluded QSBS. Hold for one more year and the 100% exclusion applies within the applicable $15 million or 10-times-basis limit. NIIT may also affect the estimate, so this is not a flat 20% calculation.
At three years under the new regime, an estimated $6 million of a $12 million gain is excluded and $6 million remains taxable under the partial-exclusion rules. Have a tax professional calculate the actual federal and state result, including possible NIIT.
States That Don’t Conform
Here’s the catch. Not every state follows federal QSBS rules. If you live in one of these states, you may owe state capital gains taxes even if your federal bill is zero:
- California. Does not conform to Section 1202 at all. You’ll owe California capital gains (up to 13.3%) on the full amount.
- Alabama. Does not conform.
- Mississippi. Does not conform.
- Pennsylvania. Does not conform.
Note: New Jersey enacted QSBS conformity in June 2025, effective for tax years beginning January 1, 2026.
California is the most impactful here. If you’re a founder in San Francisco sitting on $10M in QSBS-eligible gains, you could owe $0 federally and $1.3M to California.
Some founders relocate before an exit to avoid this. That’s a personal decision, but it’s one you should make deliberately, not discover after the fact.
What You Should Do Now
1. Check Your Entity Structure
QSBS only applies to C-corps. If you’re an LLC (even one taxed as an S-corp), you don’t qualify. If you’re pre-revenue and considering your structure, the QSBS benefit is a strong argument for C-corp incorporation. But there are tradeoffs. Talk to a tax advisor.
How to Value a Startup for Equity
2. Track Your Holding Period
With the new tiered system, the difference between 2 years 11 months and 3 years 1 month is the difference between $0 and millions in tax savings. Know your dates. If you’re approaching an exit, the holding period should be part of the negotiation timeline.
3. File Your 83(b) Election
If you receive restricted stock, file your 83(b) election within 30 days. This starts your QSBS holding clock at the grant date instead of the vesting date. On a four-year vesting schedule, that’s the difference between qualifying at year four (grant date + 4 years) and year eight (last vesting date + 4 years).
4. Document Your Gross Assets
If your company is approaching the applicable $75M or $50M threshold, keep records. The test is measured before and immediately after issuance, so the timing of stock issuance relative to a fundraise can matter.
5. Consider C-Corp Conversion
If you’re currently an LLC and planning to raise institutional money, the combination of investor preference and QSBS benefits makes a strong case for conversion. The C-corp must not exceed the applicable gross-assets ceiling before or immediately after issuance. If you’ve been using dynamic equity during the LLC phase, the LLC-to-C-corp QSBS strategy walks through sequencing, the equity freeze point, and Section 1202’s special fair-market-value basis rule for contributed property.
The Bottom Line
QSBS was already one of the best tax benefits available to startup founders. The One Big Beautiful Bill Act made it meaningfully better. A shorter holding period, a higher exclusion cap, and a more generous asset threshold all work in your favor.
But it only works if your company is structured correctly and you’ve done the paperwork. Check your entity type. File your 83(b). Track your dates. And if you’re in California, factor state taxes into your planning.
Equity Matrix helps you track your equity from day one, so when QSBS qualification matters, you have the records to prove it.
FAQ
Does my LLC qualify for QSBS?
No. QSBS under Section 1202 applies only to qualifying stock issued by a C-corporation. You’d need to convert to a C-corp, and its gross assets must not exceed the applicable $75M or $50M ceiling before and immediately after issuance.
What if I’m in California?
California does not conform to Section 1202. Even if your gains are fully excluded at the federal level, you’ll owe California state capital gains tax (up to 13.3%) on the full amount. This is one reason some founders consider relocating before a liquidity event. Plan for this early.
Can I claim QSBS retroactively on stock I already hold?
The new tiers, $15 million cap, and $75 million ceiling apply only to QSBS acquired after July 4, 2025. Stock acquired on or before July 4, 2025 stays under the old regime: no exclusion before five years, then the applicable exclusion subject to the $10 million or 10-times-basis cap and $50 million ceiling. Confirm qualification and dates with a tax advisor; this article is educational, not legal or tax advice.
Ready to split equity fairly?
Equity Matrix tracks contributions and calculates ownership automatically.
Get Started FreeThis article is for informational purposes only and does not constitute legal, tax, or financial advice. Equity Matrix is not a law firm, accounting firm, or financial advisor. Consult a qualified professional for guidance specific to your situation.
Co-founder, Equity Matrix
Sebastian writes about startup equity, founder dynamics, and building fair partnerships.
Keep reading
Should you exercise your stock options before leaving a job?
Leaving a startup with vested options? Your plan sets the exercise deadline, while ISO status generally lasts three months. Here's how to decide.
Read more →The dynamic equity playbook: LLC to C-corp to exit
You don't have to choose between dynamic equity flexibility and potential C-corp tax benefits. Start with an LLC, convert when ready, and plan for QSBS.
Read more →