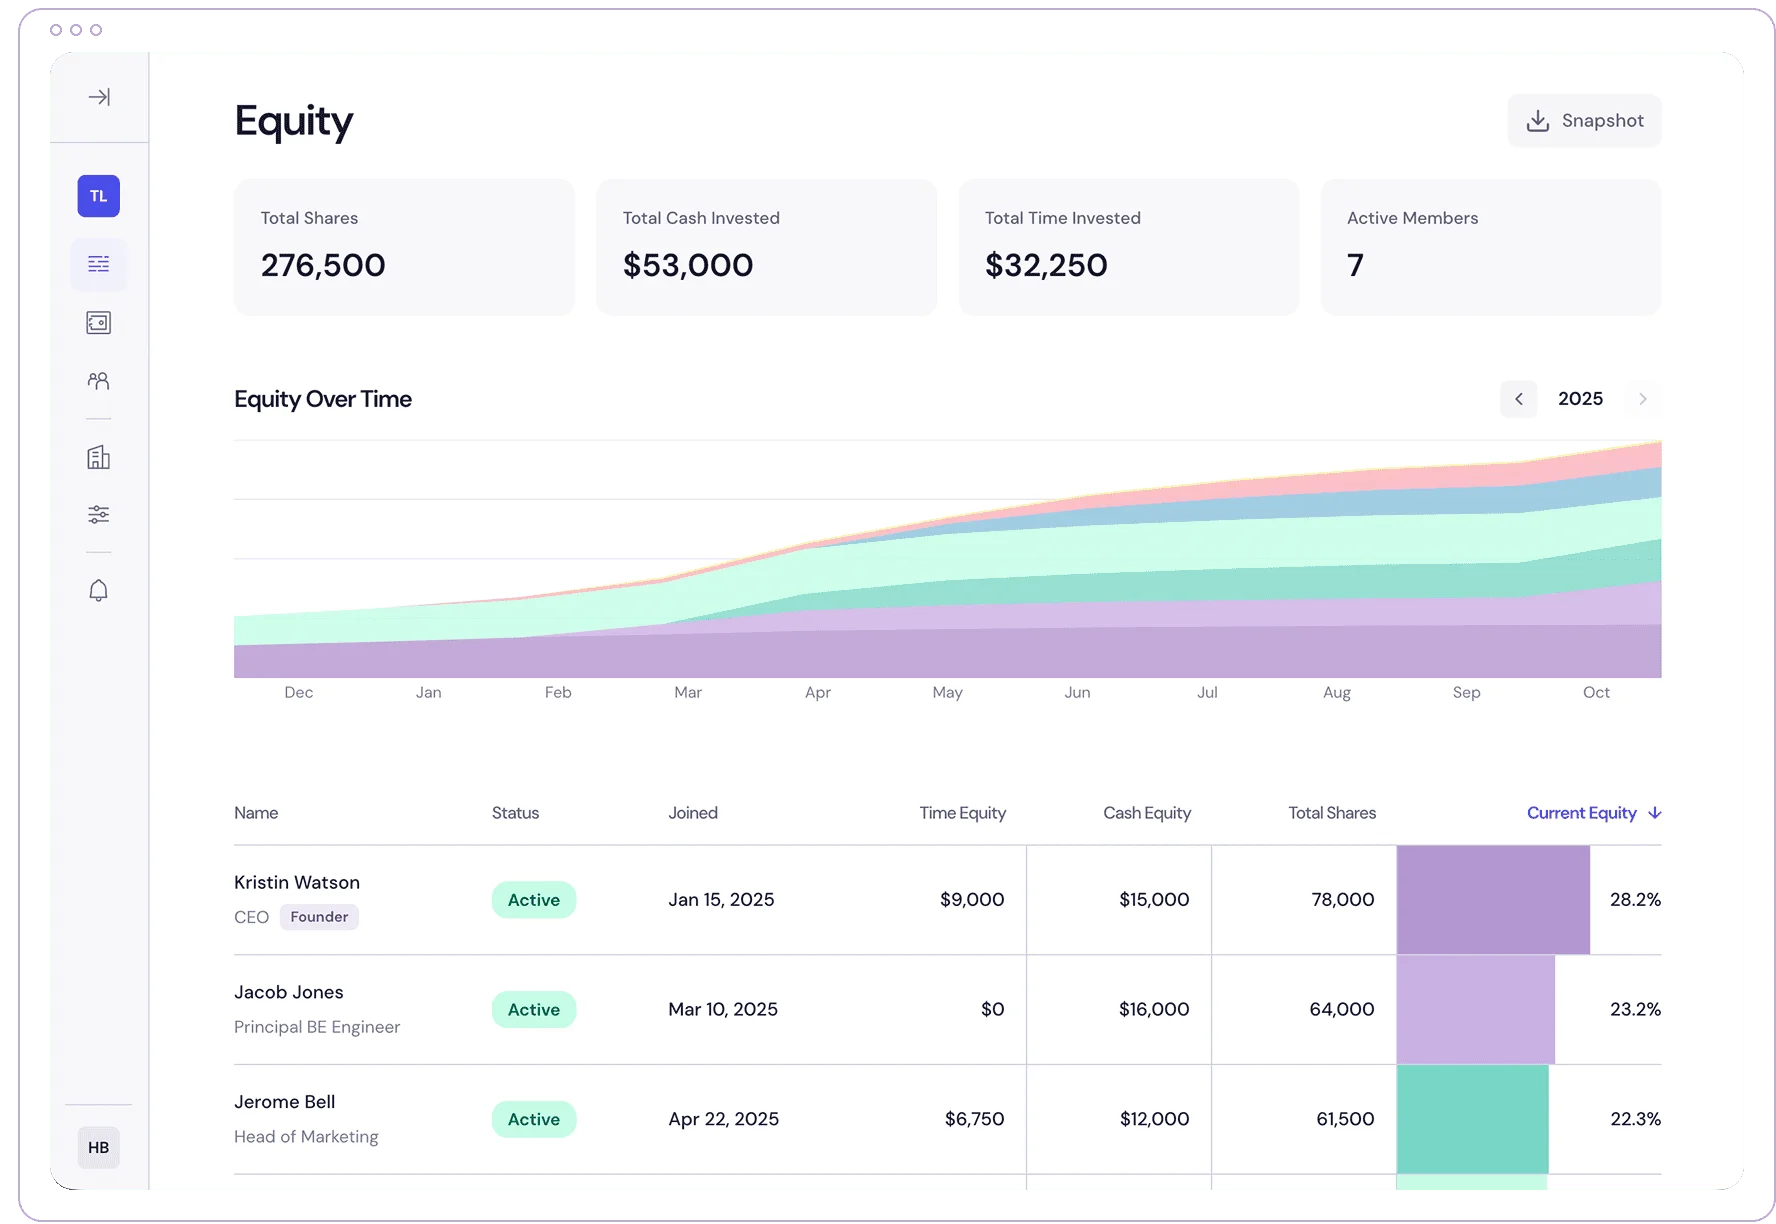
Startup valuation is relevant when you price shares or options, negotiate with investors, or complete another transaction that depends on fair market value. Founders do not legally need a company valuation merely to agree on percentage ownership.
If you’ve never raised money, the concept feels circular. How can your company be worth anything when you have no revenue, no product, and maybe no customers? A founder split can be negotiated as percentages without valuing the company. A defensible fair-market-value analysis becomes important when you price a stock option or another transaction or tax instrument makes value relevant; fundraising also introduces negotiated valuations and caps.
When a number is needed, it does not have to pretend to be perfectly precise, but the method and supporting facts matter. The equity calculator can separately help founders model ownership percentages from contributions.
Why You Need a Valuation Before You Raise
Most founders think valuation only matters when investors show up. That’s wrong. You need one much earlier than that. Here’s why.
Pricing stock options
If you plan to grant stock options to employees, advisors, or early contributors, you need a strike price. That strike price is based on the fair market value (FMV) of your common stock. Set it too low and the IRS comes knocking. Set it too high and your options aren’t attractive enough to recruit anyone. Either way, you need a defensible number.
Co-founder negotiations
When a new co-founder joins after you’ve already been building, how much of the company do they get? In a traditional fixed-equity model, the answer depends on what the company is worth when they join. Without a valuation, you’re negotiating in the dark. With one, you can calculate exactly how much equity a cash contribution, IP transfer, or sweat equity commitment represents.
If you’re using a dynamic equity model, you can skip the valuation question entirely. The new co-founder’s contributions simply get tracked alongside everyone else’s. The existing founders already have accumulated contributions, so the new person naturally starts at a smaller share and grows proportionally based on what they put in. No negotiation, no guesswork about company value.
409A compliance
If your company issues nonqualified stock options, the exercise price generally must be at least the common stock’s fair market value at grant to fit the usual Section 409A exemption. An independent appraisal is one safe harbor for establishing that value, not a universal legal requirement. A reasonable board valuation can comply, although it may lack the appraisal safe harbor.
Investor conversations
Even if you’re not actively fundraising, having a sense of your company’s value helps you evaluate whether an investor’s term sheet is reasonable. A SAFE with a $3M cap means something very different depending on whether your company is worth $500K or $2.5M.
Common Valuation Methods for Pre-Revenue Startups
There’s no single formula. Instead, there are several methods designed for companies that don’t yet have revenue or profits to analyze. Each has strengths and limitations.
| Method | How It Works | Best For | Typical Range |
|---|---|---|---|
| Berkus Method | Assigns up to $500K for each of five risk factors (idea, team, prototype, relationships, sales) | Very early stage, pre-product | Up to $2.5M |
| Scorecard Method | Adjusts the average valuation of comparable funded startups based on your team, market, and product | Angel/seed stage with regional data | $1M to $5M |
| Venture Capital Method | Works backward from a projected exit value and the investor’s target return | Startups negotiating with VCs | Varies widely |
| Cost-to-Duplicate | Estimates the cost of rebuilding your product, tech, and team from scratch | Tech-heavy startups with defensible IP | Based on actual costs |
| Comparable Transactions | Uses recent funding rounds of similar companies as benchmarks | Any stage with comparable data available | Market-dependent |
Berkus Method
Developed by angel investor Dave Berkus, this method assigns up to $500K for each of five value drivers: idea, team, prototype, strategic relationships, and early traction. Add them up and you get a pre-money valuation capped at $2.5M. It’s simple and fast, but the $500K-per-category ceiling is somewhat arbitrary and doesn’t account for market size.
Scorecard Method
Created by angel investor Bill Payne, this method starts with the average pre-money valuation of recently funded startups in your region and sector, then adjusts based on weighted factors: team strength (30%), market size (25%), product stage (15%), competitive environment (10%), partnerships (10%), and other factors (10%). Score above average on the important factors and your valuation goes up. Below average and it goes down.
Venture Capital Method
This one works backward from a projected exit. Estimate your exit value (say, $100M via acquisition in seven years), then apply the investor’s target return (often 10x to 20x). If they want 10x, your post-money valuation today is $10M. Subtract the investment amount and you get pre-money. It’s useful in fundraising conversations but less helpful for internal equity decisions.
Cost-to-Duplicate
What would it cost someone to build exactly what you’ve built from scratch? This method tallies development costs, patent filings, research expenses, and the opportunity cost of the founders’ time. The result is a floor valuation, not a ceiling. It’s most useful for startups with significant technical IP.
Comparable Transactions
Look at what similar startups raised at similar stages. If three SaaS companies in your space raised seed rounds at $4M to $6M pre-money, that’s your benchmark. The challenge is finding truly comparable companies.
409A valuations: what they are and when you need one
A 409A valuation commonly means an appraisal or other defensible determination of common stock fair market value used when applying Section 409A. A formal independent appraisal is popular because it can provide a safe harbor, but the statute does not require that specific method.
Who needs one
A company generally needs defensible fair-market-value support when pricing stock options or other awards whose Section 409A treatment depends on value. This is not a rule that every equity award needs an independent appraisal. RSUs have no strike price, and restricted stock is generally governed by Section 83 rather than Section 409A, although particular arrangements can raise separate deferred-compensation issues.
What happens if you skip it
If a nonqualified option is granted below fair market value, it may become subject to Section 409A and expose the holder to accelerated income inclusion and additional tax. The problem is below-FMV pricing, not the absence of an appraisal by itself. A reasonable valuation method may comply even without an independent appraisal.
How often you need one
At minimum, every 12 months. You also need a new one after any “material event” that changes your company’s value. Closing a funding round, launching a product, signing a major customer, or bringing on a co-founder with a large equity grant can all trigger the need for a refresh.
What it costs
Expect to pay between $1,200 and $10,000 depending on your company’s stage and complexity. Early-stage companies with simple cap tables pay less. Companies with multiple share classes, convertible notes, and SAFEs pay more. Providers like Carta, Pulley, and AngelList offer 409A services bundled with their cap table management tools.
Safe harbor protection
An independent appraisal is one valuation safe harbor. The regulations also recognize an illiquid-startup safe harbor and a binding-formula safe harbor when their requirements are met. A reasonable board valuation can comply without a safe harbor, but it does not receive the same presumption. Counsel should confirm which method fits the company and award.
How Valuation Affects Equity Decisions
Your company’s valuation directly determines how much ownership each equity grant represents.
Example: You’re granting 5% to a new hire. If your company is valued at $1M, that 5% is worth $50,000 on paper. If you’ve inflated your valuation to $5M, that same 5% is “worth” $250,000, but it may not reflect reality.
Overvaluation makes grants look generous on paper, but employees will eventually realize the number was inflated. It also makes your cap table harder to manage because future investors will expect a valuation that reflects actual progress.
Undervaluation makes each percentage point cheaper, which is great for recruiting. But it can trigger IRS problems if you’re issuing options below fair market value.
The goal isn’t to maximize or minimize. It’s to arrive at a number that’s defensible, fair, and useful for making decisions.
How it affects ISOs
For incentive stock options specifically, the strike price must be at or above fair market value on the grant date. A below-FMV grant fails the ISO pricing requirement and is treated as a nonqualified option; because it is discounted, it may also create a Section 409A problem. That is more than merely receiving less favorable ISO tax treatment.
How it affects co-founder splits
In a traditional fixed-equity model, when a co-founder joins after the company has been building for a while, valuation determines how much their contribution is “worth” relative to what’s already been built. If you’ve been working for six months and the company is valued at $200K, a co-founder investing $50K is buying roughly 20% of the existing value (before accounting for their future contributions). Without a valuation, that negotiation is just guesswork.
With a dynamic equity model, the valuation question becomes less important for co-founder splits. Instead of negotiating percentages based on what the company is worth today, you track what everyone contributes over time and let the math determine ownership. The original founder’s prior work is already reflected in their accumulated contributions. A new co-founder’s contributions simply get added to the pool. Equity Matrix handles this automatically, so you can skip the valuation debate entirely for internal equity decisions.
Dynamic Equity: An Alternative to Valuation-Based Splits
Here’s something worth considering. If you’re splitting equity among co-founders at the earliest stages, you might not need a formal valuation at all.
Dynamic equity models like Equity Matrix sidestep the valuation problem entirely. Instead of asking “what is the company worth?”, they ask “what has each person contributed?”
Every contribution gets tracked at an agreed-upon rate. Your ownership percentage at any point reflects your share of total contributions. No one has to guess what the company is worth because ownership is based on inputs, not outputs.
This is especially useful when a formal valuation would be meaningless. Two founders in a garage haven’t built anything that can be valued with the Berkus Method. But they can track who’s doing what.
When the company matures enough to need a real valuation, you can convert the dynamic split into a fixed cap table. Until then, you avoid the valuation question and focus on building.
Common Mistakes Founders Make
Picking a number out of thin air
“We’re worth $5 million” is not a valuation. It’s a wish. Without a method behind the number, you have no credibility with investors and no basis for equity negotiations. Even a rough Berkus or Scorecard analysis is better than nothing.
Overvaluing to feel good
A high valuation feels validating, but it sets expectations you may not meet. If you raise at a $10M valuation and your next round only supports $8M, you’re in a down round. That’s painful for everyone, especially early employees whose options end up underwater.
Confusing investor valuation with fair market value
The valuation cap on your SAFE note is not the same as your company’s FMV. Your 409A valuation will almost always be lower than your fundraising valuation. Common stock has fewer rights and less liquidity than preferred stock, so it’s worth less per share. This is normal and expected.
Using unsupported fair market value
A reasonable, documented board valuation can comply even if it does not qualify for a safe harbor. Independent appraisal, illiquid-startup, and binding-formula methods can provide safe harbors when their conditions are satisfied. The right approach depends on the company and transaction, so have counsel or a qualified tax advisor review it.
Setting it and forgetting it
Your valuation changes as your company grows, raises money, and hits milestones. Using a stale valuation to price new option grants is a recipe for problems. Your employee equity benchmarks and grant sizes should evolve as the valuation changes.
Not understanding dilution
Every time you issue new shares, everyone else’s percentage goes down. Founders who don’t model this end up surprised when they own far less than expected after a few rounds. Track this in your cap table from day one.
FAQ
Do I need a formal valuation to split equity with my co-founders?
Not necessarily. Founders do not legally need a company valuation merely to agree on percentages. Many founding teams use contribution-based models like Slicing Pie or Equity Matrix. A defensible FMV determination becomes important when pricing options or when another transaction or tax instrument makes value relevant; fundraising valuation is a separate negotiated question.
What’s the difference between pre-money and post-money valuation?
Pre-money valuation is what your company is worth before new investment. Post-money valuation is pre-money plus the investment amount. If your pre-money is $4M and an investor puts in $1M, your post-money is $5M, and the investor owns 20%. This distinction matters a lot when negotiating with investors and understanding dilution.
How often should I update my company’s valuation?
If you rely on an appraisal safe harbor while issuing options, refresh it as required and after a material event. Other compliant valuation methods have their own conditions. Stale or unsupported fair market value can lead to mispriced options.
Can I do my own 409A valuation?
The IRS permits a reasonable board-determined valuation; a formal independent appraisal is not legally required. An appraisal is a common safe harbor, while qualifying illiquid-startup and binding-formula valuations are other safe harbors. Ask counsel which method is available and appropriate.
The Bottom Line
Valuing a startup for equity purposes isn’t about finding the “right” number. It’s about arriving at a defensible number that lets you make fair decisions about ownership, compensate your team appropriately, and stay on the right side of the IRS.
Use the methods that fit your stage. Establish and document fair market value appropriately before pricing options; an independent appraisal is one route, not the only lawful one. Don’t inflate your valuation to impress people. And if you’re in the earliest days and no transaction requires a company valuation, consider a dynamic equity approach that tracks contributions instead.
The companies that handle valuation thoughtfully are the ones that attract better talent, negotiate better deals, and avoid the co-founder conflicts that kill startups before they ever get off the ground.
How to Split Equity in a Startup
Equity Matrix helps founding teams track contributions, model ownership splits, and manage their cap table from day one, so equity decisions are based on data instead of guesswork.
Ready to split equity fairly?
Equity Matrix tracks contributions and calculates ownership automatically.
Get Started FreeThis article is for informational purposes only and does not constitute legal, tax, or financial advice. Equity Matrix is not a law firm, accounting firm, or financial advisor. Consult a qualified professional for guidance specific to your situation.
Co-founder, Equity Matrix
Sebastian writes about startup equity, founder dynamics, and building fair partnerships.
Keep reading
Startup cap table: how to build, manage, and not mess it up
A step-by-step guide to building your startup's cap table from scratch, managing it through funding rounds, and avoiding the mistakes that cost founders equity.
Read more →What is a cap table (and why it matters)
A cap table tracks who owns what in your company. Here's what it includes, why investors care about it, and how to manage it from day one.
Read more →