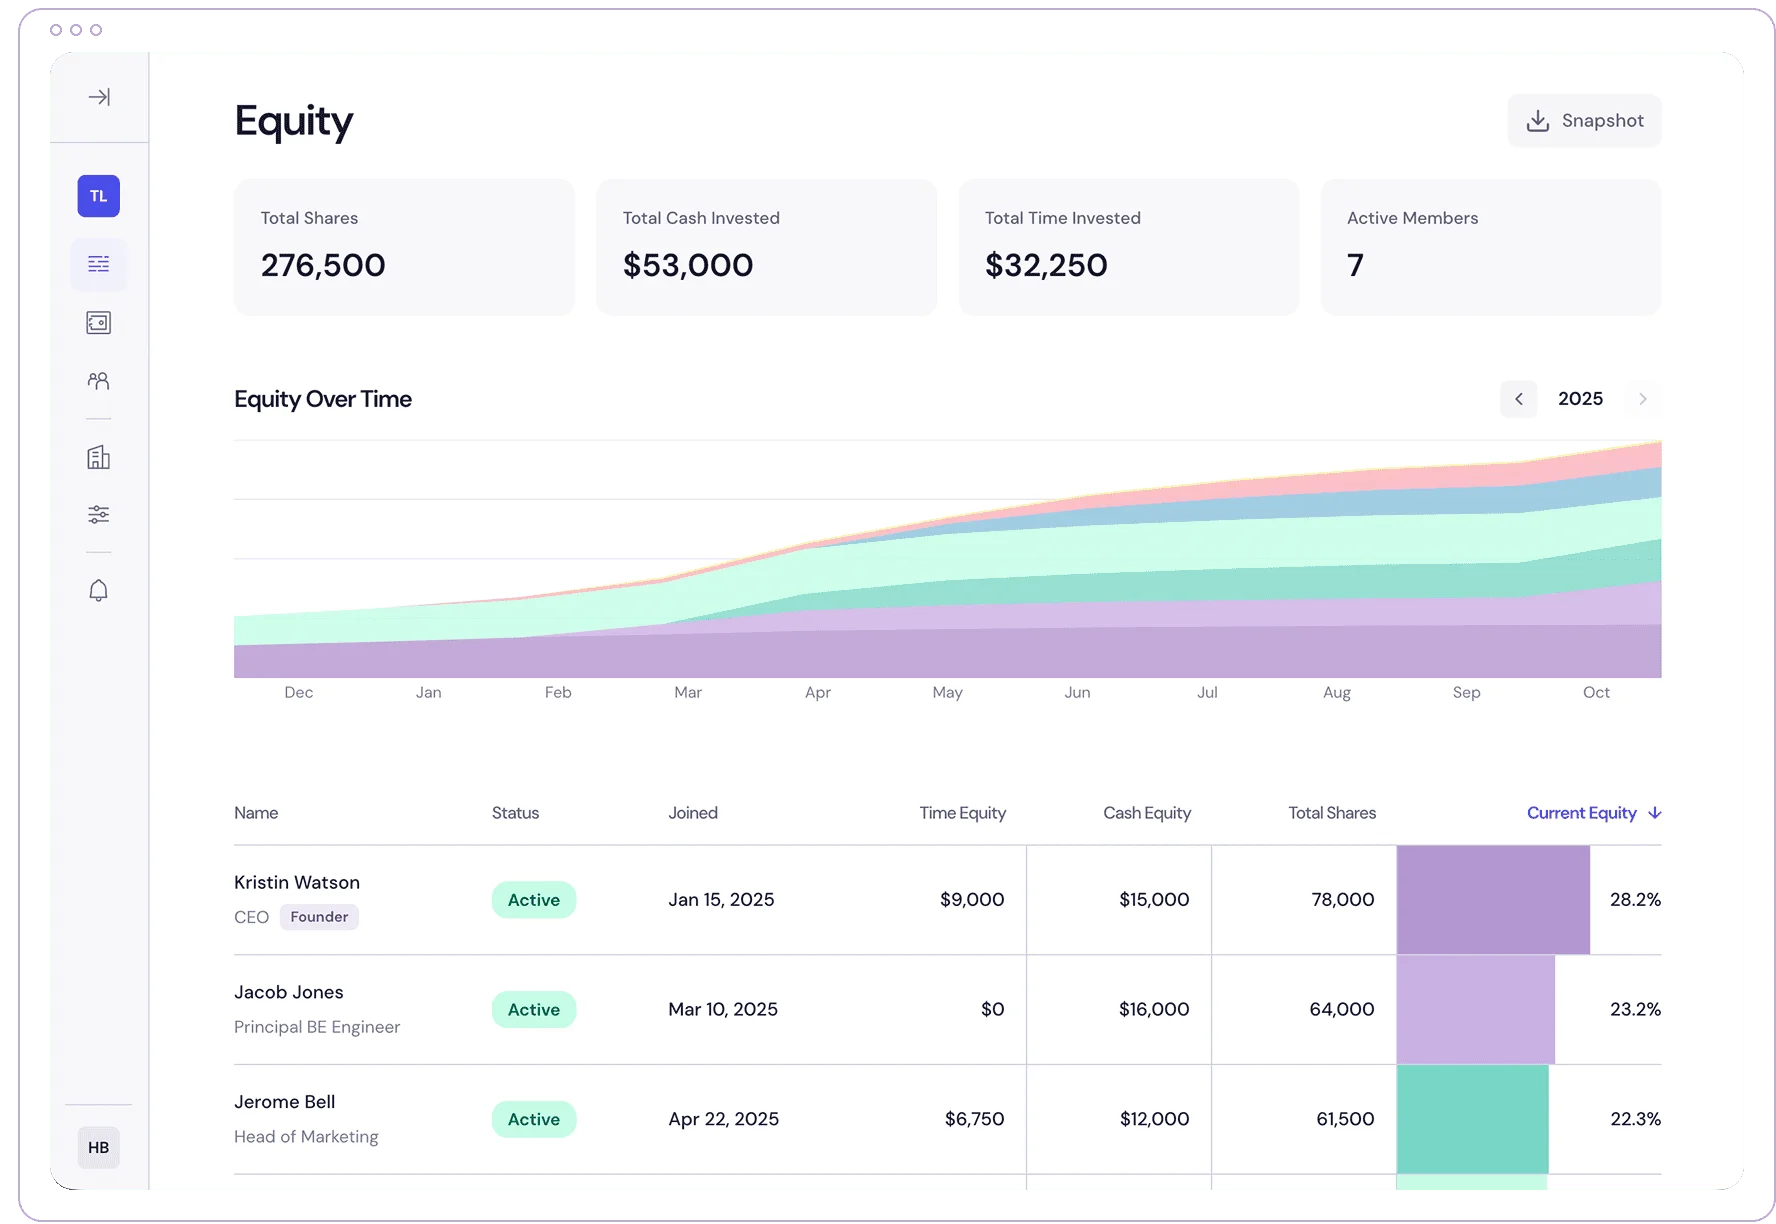
A SAFE (Simple Agreement for Future Equity) is a fundraising instrument where an investor gives a startup money now in exchange for the right to receive equity later, typically when a priced round occurs.
SAFEs are everywhere in early-stage fundraising. If you’re raising a pre-seed or seed round, chances are someone will hand you a SAFE. And if you don’t understand exactly how it works, you’re signing away more of your company than you think — use the equity calculator to model the dilution before you accept any terms.
The document is short. The math is not obvious. That’s by design.
Quick Reference: SAFE Terms
| Term | Definition |
|---|---|
| Valuation Cap | Maximum valuation at which the SAFE converts to equity |
| Discount Rate | Percentage discount on the price-per-share at the next round |
| MFN Clause | ”Most Favored Nation” — lets an investor adopt a later SAFE’s terms as a complete package |
| Pro Rata Rights | Right to invest more in the next round to maintain ownership percentage |
| Conversion Trigger | Event that converts the SAFE to actual equity (usually a priced round) |
A Brief History
Y Combinator created the SAFE in 2013 to solve a real problem: convertible notes were too complicated for early-stage deals.
Convertible notes are debt. They have interest rates, maturity dates, and default provisions. For a pre-seed startup that might not raise again for two years, carrying debt with a maturity date creates unnecessary pressure and legal complexity.
SAFEs stripped all that away. No interest. No maturity date. No debt on the balance sheet. Just a simple promise: give us money now, get equity later.
The simplicity worked. SAFEs became the default instrument for early-stage fundraising, especially among Y Combinator-affiliated startups. In 2018, Y Combinator updated the SAFE to a “post-money” version, which changed the dilution math significantly. More on that below.
How SAFEs Work
The mechanics are straightforward in concept.
Step 1: An investor writes you a check. Let’s say $200,000.
Step 2: You give them a SAFE — a one-page-ish agreement with specific terms (usually a valuation cap, a discount, or both).
Step 3: Nothing happens to your cap table. The investor doesn’t own shares yet. The SAFE sits as an obligation on your books.
Step 4: A “trigger event” occurs. This is almost always a priced equity round (Series A, for example). At this point, the SAFE converts into actual shares.
Step 5: The conversion terms determine how many shares the investor gets — and that’s where the details matter.
Key Terms Explained
Valuation Cap
The cap is the maximum valuation used to calculate the investor’s share price at conversion. It protects the early investor from excessive dilution if your valuation skyrockets.
Example: An investor puts in $200,000 on a SAFE with a $5M cap. You raise a Series A at a $20M valuation. Without the cap, their $200K would buy shares at the $20M price. With the cap, they convert at $5M — getting 4x more shares.
The cap is the investor’s upside. A lower cap is better for the investor, worse for you.
Discount Rate
A discount gives the SAFE investor a percentage reduction on whatever price-per-share the next round’s investors pay. The standard discount is 20%.
Example: Series A investors pay $2.00 per share. A SAFE with a 20% discount converts at $1.60 per share. The early investor gets more shares per dollar.
Cap + Discount
Many SAFEs include both. When they do, the investor gets whichever produces more shares — the cap or the discount. They don’t stack.
MFN (Most Favored Nation)
If you issue a later SAFE with preferable terms, an MFN clause can let the earlier investor amend its SAFE to adopt that later SAFE’s terms as a complete package. It does not let the investor cherry-pick individual favorable terms from different SAFEs.
Pro Rata Rights
The right to invest additional money in the next priced round to maintain the same ownership percentage. This matters more than most founders realize — it means the investor can prevent dilution at every subsequent round.
How SAFEs Convert to Equity
Let’s walk through a detailed example.
Setup (simplified, with no options, other SAFEs, or notes):
- You raise $500,000 on one SAFE with a $5M post-money valuation cap
- Six months later, you raise a $2M Series A at a $15M pre-money valuation
- Founders hold 10,000,000 shares before conversion
SAFE conversion:
The SAFE converts using the cap because it produces the better price. A post-money SAFE’s percentage is the purchase amount divided by the SAFE’s defined “Company Capitalization”: $500,000 / $5,000,000 = 10%. That capitalization is post all SAFEs and converting notes and includes issued and promised options plus the existing unissued pool, but it excludes the new-money shares and any option-pool increase made for the priced round.
With founders representing the other 90%, Company Capitalization is 10,000,000 / 90% = 11,111,111 shares.
SAFE shares are 10% x 11,111,111 = approximately 1,111,111 shares. Equivalently, the SAFE price is $5,000,000 / 11,111,111 = $0.45 per share, and $500,000 / $0.45 = approximately 1,111,111 shares.
Series A price: $15,000,000 / 11,111,111 pre-round shares = $1.35 per share.
Series A shares issued: $2,000,000 / $1.35 = approximately 1,481,481 shares.
Post-round ownership:
| Holder | Shares | Ownership |
|---|---|---|
| Founders | 10,000,000 | ~79.4% |
| SAFE investor | ~1,111,111 | ~8.8% |
| Series A investors | ~1,481,481 | ~11.8% |
| Total | ~12,592,592 | 100% |
Immediately before the new-money financing, the SAFE represents 10% of Company Capitalization. The new Series A shares dilute it to about 8.8% and dilute founders to about 79.4%. Any option-pool increase for the round would dilute both further.
How Multiple SAFEs Stack and Dilute
Here’s where founders get surprised.
Most seed-stage startups don’t raise one SAFE. They raise several, often at different terms and different times. Each SAFE is an independent conversion event that happens simultaneously at the trigger.
The stacking problem:
| SAFE | Amount | Cap |
|---|---|---|
| SAFE 1 (angel) | $100,000 | $4M |
| SAFE 2 (pre-seed fund) | $300,000 | $6M |
| SAFE 3 (accelerator) | $150,000 | $8M |
| Total raised | $550,000 |
Each SAFE converts at its own cap, meaning each gets a different share price. SAFE 1 gets the best price (lowest cap), SAFE 3 gets the worst.
When all three convert at a Series A, the combined dilution is larger than most founders expect — often 15-25% for the SAFE stack alone, before the Series A investors take their share.
By the time the Series A closes, founders who thought they’d retain 70% might be looking at 55-60%. And that’s with a single round of SAFEs.
Post-Money vs. Pre-Money SAFEs
This is the most important distinction in SAFE mechanics, and it’s the one most founders miss.
Pre-Money SAFEs (Original, Pre-2018)
The original SAFE was “pre-money.” The valuation cap applied to the company’s value before the SAFE money was included. This made dilution calculations ambiguous — especially with multiple SAFEs — because each SAFE’s conversion affected the others.
Post-Money SAFEs (Current Standard)
In 2018, Y Combinator introduced the post-money SAFE. The valuation cap now includes the SAFE investment itself.
This is cleaner mathematically but worse for founders.
With a $5M post-money cap and a $500K investment, the SAFE represents approximately 10% ($500K / $5M) of the SAFE’s defined Company Capitalization immediately before the priced round. That percentage is not post-financing ownership: the new round and any new option pool dilute the SAFE holder. Other post-money SAFEs generally dilute founders rather than one another under the standard mechanics.
Example with post-money SAFEs:
| SAFE | Amount | Post-Money Cap | Investor Ownership |
|---|---|---|---|
| SAFE 1 | $200,000 | $5M | 4.0% |
| SAFE 2 | $300,000 | $5M | 6.0% |
| SAFE 3 | $500,000 | $8M | 6.25% |
| Total | $1,000,000 | 16.25% |
Before the Series A’s new money and any pool increase, the SAFE stack represents approximately 16.25% of the defined capitalization. The priced round and its pool increase then dilute both founders and SAFE holders.
Post-money SAFEs make the math transparent. Use that transparency to model exactly how much dilution you’re signing up for.
When to Accept a SAFE vs. Other Instruments
SAFEs are not the only option. Here’s how they compare. And the fundraising landscape around SAFEs may be shifting: the INVEST Act passed by the House would raise the Regulation Crowdfunding cap from $5M to $10M, expand who qualifies as an accredited investor, and explicitly clarify demo day rules — changes worth watching if you’re planning a SAFE raise.
SAFE vs. Convertible Note
Convertible notes are debt. They have interest rates (usually 2-8%) and maturity dates (usually 18-24 months). If the note matures before a priced round, you technically owe the money back.
SAFEs avoid this. No interest, no maturity, no default risk. For most pre-seed and seed startups, SAFEs are simpler and safer.
Choose a convertible note if: The investor insists (some do), or you want the interest accrual to slightly reward early investors without lowering the cap.
SAFE vs. Priced Round
A priced round means selling actual shares at a specific valuation. It requires more legal work, a board seat discussion, and often a lead investor.
At pre-seed, the overhead isn’t worth it. At seed, it depends on the round size. At Series A, you should absolutely be doing a priced round.
Choose a priced round if: You’re raising more than $1-2M, you have a lead investor, and you want clean cap table clarity.
SAFE vs. Equity Grant
If someone is contributing work (not cash), a SAFE is the wrong instrument. Dynamic equity or direct equity grants are better for co-founders and early contributors.
How Dynamic Equity Interacts with SAFE Fundraising
If you’re using a contribution-based equity model pre-investment, here’s how the pieces fit together.
Before the SAFE: Dynamic equity tracks co-founder contributions and determines relative ownership. If three founders have contributed and the model says the split is 45/35/20, that’s their relative ownership of 100% of the company.
When you accept a SAFE: The SAFE sits on top of the existing equity structure. It doesn’t change the co-founders’ relative split — it dilutes everyone proportionally when it converts.
At conversion: If the SAFE represents 10% of Company Capitalization immediately before the priced round, the founders collectively represent 90% at that point. Their relative split stays the same: 45/35/20 becomes 40.5/31.5/18 before new-money and pool dilution. The priced round then dilutes everyone in that pre-round capitalization.
This is actually one of the cleanest ways to handle early fundraising. The dynamic model handles the messy, evolving co-founder split. The SAFE handles the investment. Each instrument does what it’s designed for.
Equity Matrix supports this workflow — track contributions dynamically, then model SAFE dilution scenarios before you sign anything.
What Founders Need to Know Before Signing
-
Model the dilution. Don’t sign a SAFE without calculating exactly how much of your company you’re giving up. Include all existing SAFEs in the model.
-
Understand post-money vs. pre-money. If someone hands you a post-money SAFE, the dilution math is explicit. Read it.
-
Watch for stacking. Multiple SAFEs at different caps create complex conversion scenarios. The combined dilution is always more than founders expect.
-
Negotiate the cap, not the discount. The cap almost always determines the conversion price. The discount is a secondary protection.
-
Know your pro rata obligations. If you give an investor pro rata rights, you’re giving them the ability to maintain their percentage at every future round. That’s a long-term commitment.
-
Get legal review. SAFEs are standardized, but terms vary. Have a lawyer review every SAFE before signing.
Frequently asked questions
What is the difference between a SAFE note and a convertible note?
A SAFE is not debt — it has no interest rate, no maturity date, and no repayment obligation. A convertible note is a loan that converts to equity, typically carrying 2-8% interest and an 18-24 month maturity date. SAFEs are simpler and avoid the legal pressure of a maturity deadline, which is why they have become the default for pre-seed and seed rounds. Convertible notes are still used when investors prefer the added protections of a debt instrument.
How much dilution should founders expect from SAFE notes?
It depends on how many SAFEs you issue, their terms, the defined Company Capitalization, and the priced round. A $500K SAFE at a $5M post-money cap represents approximately 10% of that defined capitalization before new-money and the round’s option-pool increase; both later dilute the SAFE holder. Use the equity calculator to model all outstanding instruments before signing.
What is a post-money SAFE and why does it matter?
A post-money SAFE, introduced by Y Combinator in 2018, makes the SAFE’s pre-financing percentage more transparent. A $200K investment on a $5M post-money cap represents approximately 4% of the SAFE’s defined Company Capitalization before new-money and the round’s option-pool increase. It is not guaranteed post-round ownership because the priced round and new pool dilute it. Understanding this distinction is critical before you accept any terms.
Can you negotiate the terms of a SAFE note?
Yes. While the Y Combinator SAFE template is standardized, the key economic terms — valuation cap, discount rate, pro rata rights, and MFN clauses — are all negotiable. Focus your negotiation on the valuation cap, since it almost always determines the conversion price. A higher cap means less dilution for founders. Also pay attention to pro rata rights, which give the investor the ability to maintain their ownership percentage at every future round and can limit your flexibility in later fundraises.
The SAFE was designed to make early fundraising simple. It succeeded. But simple doesn’t mean free. Every SAFE you sign is a claim on your company’s future equity. Make sure you understand the cost before you cash the check.
Ready to split equity fairly?
Equity Matrix tracks contributions and calculates ownership automatically.
Get Started FreeThis article is for informational purposes only and does not constitute legal, tax, or financial advice. Equity Matrix is not a law firm, accounting firm, or financial advisor. Consult a qualified professional for guidance specific to your situation.
Co-founder, Equity Matrix
Sebastian writes about startup equity, founder dynamics, and building fair partnerships.
Keep reading
Convertible notes vs. SAFEs: which is right for you?
A practical comparison of convertible notes and SAFEs: how each works, when to use them, and how they affect founder dilution. The complete guide for early-stage fundraising.
Read more →Pro forma cap table: how to model your equity before you raise
A pro forma cap table shows who owns what after your next round closes. How to build one, with a worked example of SAFE conversion and the option pool shuffle.
Read more →