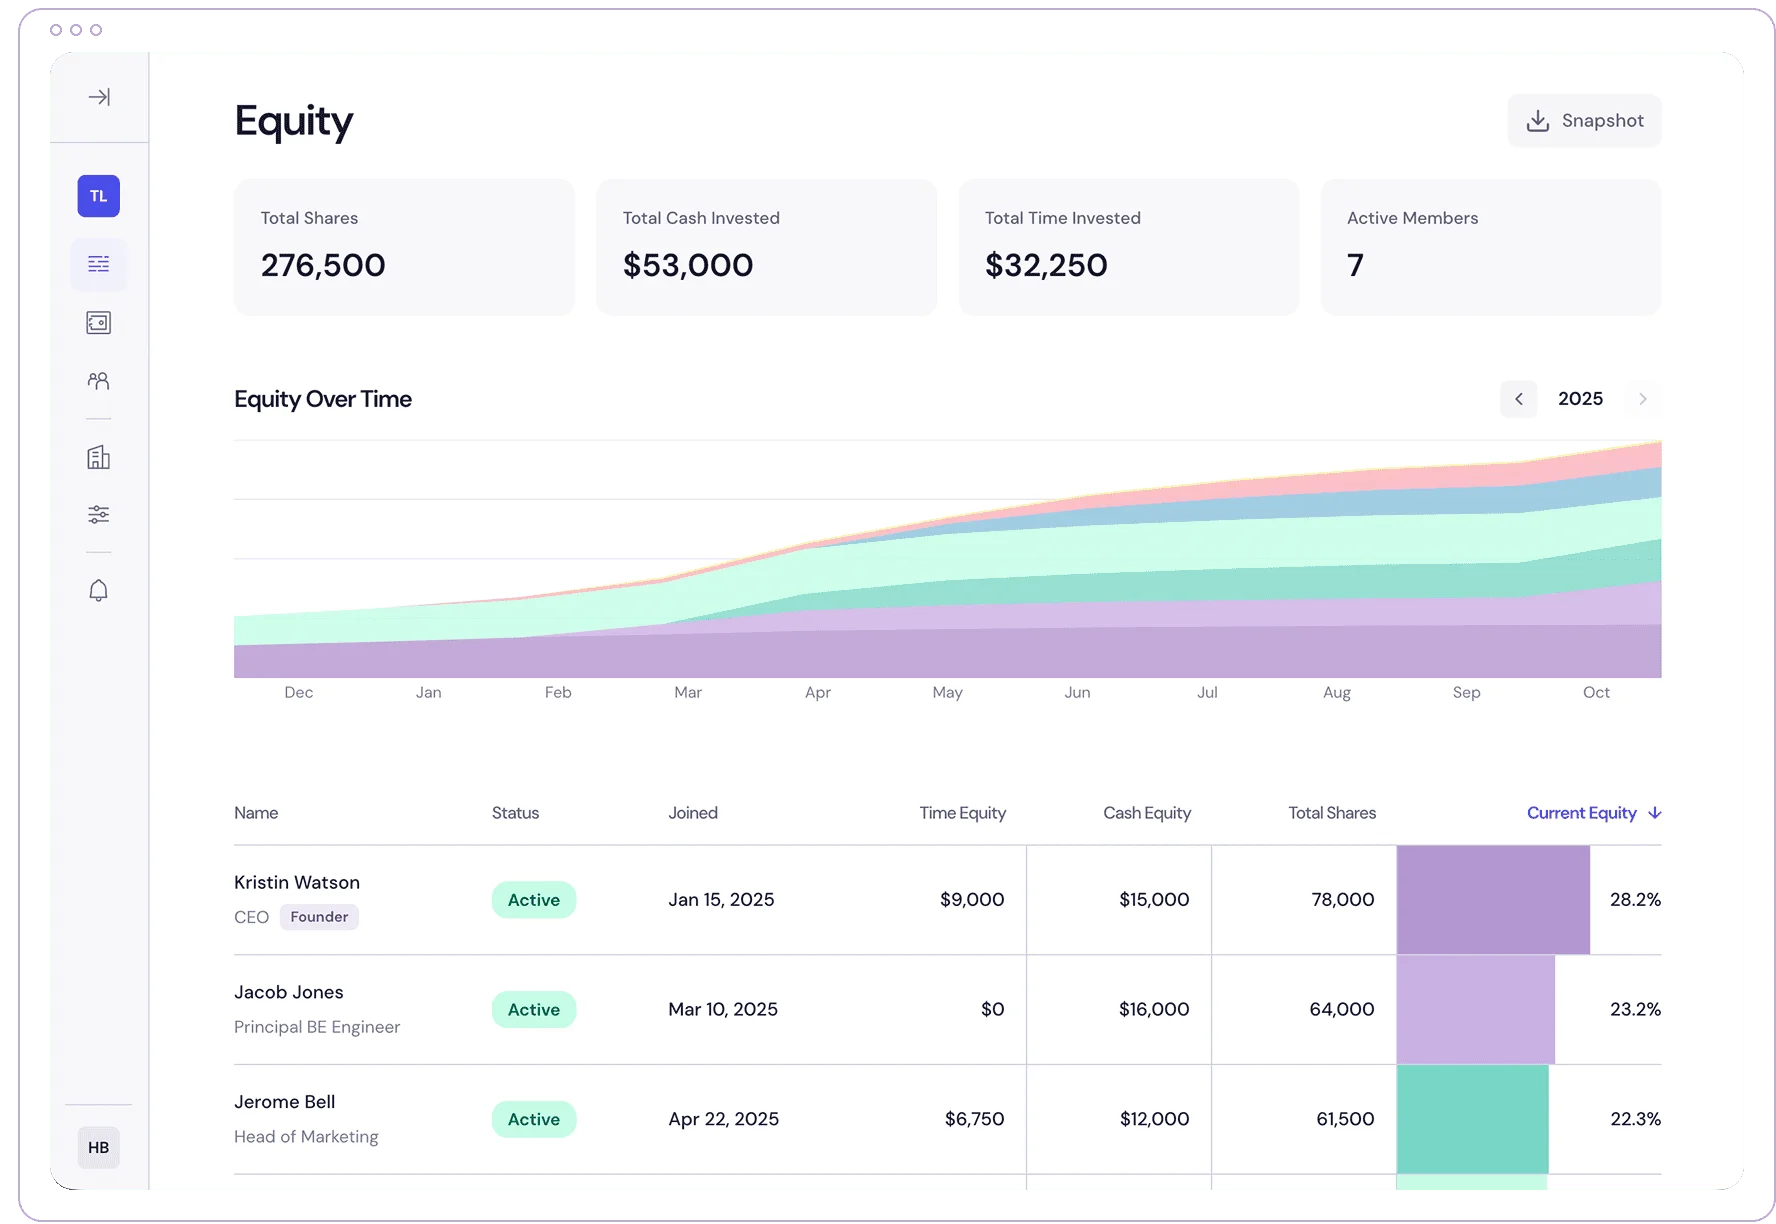
Phantom equity gives someone the financial benefit of ownership without actually making them an owner. They don’t get shares, voting rights, or a seat at the table. But when the company hits a milestone or gets sold, they get a payout based on what their ownership would have been worth.
If you run an LLC, a service business, or any company where giving away real equity is complicated or undesirable, phantom equity might be the right tool. It is one way to provide value-linked compensation without issuing actual ownership.
This guide covers how phantom equity works, when it makes sense, how it compares to real equity and dynamic equity, and the tax implications you need to understand.
What phantom equity actually is
Phantom equity (also called phantom stock, shadow equity, or phantom units) is a cash bonus plan that mimics the economics of equity ownership. The company creates fictional “units” that track the company’s value. Employees vest into those units over time. When a trigger event happens, they receive a cash payout equal to what those units would be worth if they were real equity.
What phantom equity holders get:
- A cash payout tied to the company’s value at a specific event
- The financial upside of ownership growth
What phantom equity holders don’t get:
- Actual ownership in the company
- Voting rights
- A seat on the cap table
- Any say in company decisions
- Equity-specific tax possibilities such as an 83(b) election; actual equity does not automatically receive capital-gain treatment
Phantom equity is compensation that looks like ownership but legally isn’t. That distinction matters for taxes, governance, and what happens when things go wrong.
How phantom equity works
Step 1: define the plan
The company creates a phantom equity plan that specifies:
- How many phantom units exist
- What percentage of the company’s value they represent
- What events trigger a payout (sale, revenue milestone, specific date)
- The vesting schedule for the units
Step 2: grant units to employees
Employees receive phantom unit grants, typically with a vesting schedule. A common structure is four-year vesting with a one-year cliff, mirroring standard equity vesting.
Step 3: units track company value
As the company grows, the phantom units grow in value proportionally. If an employee holds phantom units representing 5% of the company, and the company is valued at $2 million, their phantom units are worth $100,000.
Step 4: trigger event and payout
When a trigger event occurs (usually a sale, but sometimes a revenue milestone or a set date), the employee receives a cash payout equal to their phantom unit value. The company writes a check. The employee stays a W-2 employee throughout the entire process.
Phantom equity example
| Event | Detail |
|---|---|
| Grant | Employee receives 5% phantom units |
| Vesting | 4 years with 1-year cliff |
| Company value at grant | $500,000 |
| Company value at trigger | $2,000,000 |
| Payout | 5% of $2,000,000 = $100,000 cash |
| Tax treatment | Ordinary income (not capital gains) |
Why LLCs and service businesses use phantom equity
The LLC ownership problem
Giving someone actual membership units in an LLC makes them a member of the company. In an LLC taxed as a partnership, that generally means:
- They’re no longer a W-2 employee. They’re a partner.
- They receive a K-1 instead of a W-2 for taxes.
- They may owe self-employment tax on their share of profits.
- They may get voting rights, depending on state law and the operating agreement.
- Removing them from the cap table if they leave is complicated.
For many small businesses, this is a dealbreaker. You want to reward key employees and keep them motivated, but you don’t want to make them partners with voting rights and tax complications.
Phantom equity solves this. Employees stay employees. They get the financial upside without the governance and tax headaches.
Service businesses and trades
Phantom equity is especially popular in service businesses: agencies, consulting firms, HVAC companies, plumbing businesses, law firms, and accounting practices. These businesses often have:
- Steady cash flow but no plans for a venture-style exit
- Key employees whose departure would hurt the business
- Owners who want to retain full control
- No interest in the complexity of actual equity grants
A plumber who’s been with your company for 10 years and manages half your customer relationships deserves to participate in the value they helped create. Phantom equity lets that happen without making them a co-owner.
Phantom equity vs. real equity
Phantom equity vs. real equity comparison
| Factor | Phantom equity | Real equity (membership units / stock) |
|---|---|---|
| Ownership | No | Yes |
| Voting rights | No | Typically yes |
| Cap table impact | None | Yes, dilutes existing owners |
| Tax at grant | None | Possible (83(b) election may apply) |
| Tax at payout or liquidity | Ordinary compensation income | Depends on instrument; RSU value and NSO spread are generally ordinary income |
| Employee status | Stays W-2 | Becomes partner/member (LLCs) |
| Complexity to set up | Moderate | Higher |
| Complexity to unwind | Low (it’s just a bonus plan) | High (buybacks, legal docs) |
| Motivation effect | Strong | Strongest |
| Best for | LLCs, service businesses, retention | Startups, companies planning exit |
When real equity is better
If you’re building a venture-backed startup, real equity is usually the right choice. Employees who own actual shares have skin in the game in a way that phantom equity can’t fully replicate. Some appreciation may qualify for capital-gain treatment, but RSU value and the NSO exercise spread are generally ordinary compensation income. For companies planning an IPO or acquisition, real equity is the standard.
When phantom equity is better
If you’re an LLC that doesn’t plan to convert to a C-Corp, or a service business that wants to retain key employees without giving up control, phantom equity is often the better tool. It’s simpler to administer, doesn’t change anyone’s tax status, and doesn’t put anyone on your cap table.
Phantom equity vs. dynamic equity
If you’re reading this on Equity Matrix, you might be wondering how phantom equity compares to dynamic equity.
They solve different problems:
Dynamic equity is for founding teams who are splitting ownership based on contributions. Everyone is an actual owner. The split adjusts as contributions change. It’s designed for pre-revenue companies figuring out who owns what.
Phantom equity is for companies that already have an ownership structure and want to incentivize employees without diluting existing owners. Nobody new becomes an owner. It’s a cash compensation plan tied to company value.
When to use which
| Situation | Best approach |
|---|---|
| Co-founders splitting ownership pre-revenue | Dynamic equity |
| Established company rewarding key employees | Phantom equity |
| LLC that doesn’t want to make employees into members | Phantom equity |
| Early-stage team where everyone is building together | Dynamic equity |
| Company preparing to sell, wants to retain key people | Phantom equity |
| Founders who want ownership tied to actual contributions | Dynamic equity |
Some companies use both: dynamic equity among the founding team, and phantom equity for employees who join later. You can even make the phantom units themselves contribution-based. We walk through two ways to do that in combining phantom equity and dynamic equity.
Tax implications
This is where phantom equity gets tricky. The tax treatment is meaningfully worse than real equity in some scenarios.
For the employee
Phantom equity payouts are taxed as ordinary compensation income, not capital gains. In the US, federal ordinary income rates range from 10% to 37%, depending on the employee’s taxable income, plus potential state tax and employment taxes. Wages may also face the Additional Medicare Tax at applicable income levels; NIIT does not apply to wages. Do not assume actual equity is all capital gain: RSU value and the NSO exercise spread are generally ordinary income, while later appreciation may be capital gain.
There’s no 83(b) election available for phantom equity because there’s no actual property being transferred. You can’t pay taxes on a low value early and benefit from growth later.
For the company
Phantom equity payouts are generally deductible as compensation expense by the company, in the year the employee includes the payout in income. This is actually an advantage over real equity, where the company often gets no deduction. The deduction can partially offset the cost of the payout.
Payroll tax timing
Income tax is withheld when the payout happens. Social Security and Medicare (FICA) can work differently: for deferred compensation, FICA generally applies once the work is done and the units vest, even if the cash comes years later. Your payroll provider and tax advisor should plan for this.
Section 409A compliance
Phantom equity plans must comply with IRC Section 409A, which governs deferred compensation. If the plan isn’t structured correctly:
- The employee could owe taxes on the phantom units as they vest, not when they’re paid out
- A 20% penalty tax could apply on top of regular income tax
- Interest charges could accumulate from the date of vesting
409A only allows deferred compensation to be paid on specific events: a change in control, separation from service, death, disability, a specified date or fixed schedule, or an unforeseeable emergency. A plan that pays promptly once units vest (generally no later than 2.5 months after the end of the tax year in which they vest) can sometimes avoid 409A deferral rules entirely under the short-term deferral exception. Either way, the payment terms have to be fixed in the plan, not left to the company’s discretion.
Getting 409A right typically requires working with a compensation attorney or tax advisor. This isn’t a DIY area.
ERISA
A phantom plan that systematically defers pay until retirement or departure can be treated as a pension plan under ERISA. If the plan is unfunded, maintained mainly to provide deferred compensation, and limited to a select group of management or highly paid employees, it can qualify as a “top hat” plan. That’s still an ERISA plan, but it’s exempt from most of ERISA’s requirements. The company generally files a one-time statement with the Department of Labor within 120 days after the plan becomes subject to ERISA. Some sale-triggered plans fall outside ERISA as bonus arrangements, particularly when payments aren’t systematically deferred until someone leaves, but that depends on the plan’s terms and how it’s run. Your attorney can tell you which applies.
How to structure a phantom equity plan
Define the trigger events
The most common triggers:
- Sale of the company (most common for service businesses)
- Specific date (e.g., units pay out after 5 years)
- Separation from service (vested units pay out when the employee leaves, as 409A defines leaving)
- Revenue or profit milestones (e.g., company hits $5M revenue), where hitting the milestone is what vests the units and payment follows within the short-term deferral deadline
Each of these has to fit within Section 409A’s rules, so let your attorney confirm the list. Avoid triggers the company can choose to activate later, like discretionary buybacks.
Be specific. “When the company is sold” is better than “at a future liquidity event.” Ambiguity leads to disputes.
Set the vesting schedule
Standard phantom equity vesting mirrors standard equity vesting: 4 years with a 1-year cliff. But you can customize:
- Shorter schedules (2-3 years) for senior hires
- Performance-based vesting tied to revenue or profit targets
- Immediate vesting for key employees you’re trying to retain right now
Determine the valuation method
How will the company be valued when a trigger event occurs? Common methods:
- Revenue multiple (e.g., 3x annual revenue)
- EBITDA multiple (e.g., 5x EBITDA)
- Independent appraisal at time of trigger
- Book value (simpler but may undervalue the business)
Define the method in the plan. Don’t leave it to negotiation at payout time.
Cap the total phantom pool
Most companies cap phantom equity at 10-20% of the total company value. This protects the owners from excessive dilution of the payout pool. If you’ve promised 5% each to four key employees, that’s 20% of the company’s value in cash payouts at a trigger event. Make sure the business can afford it.
Common mistakes with phantom equity
Not getting 409A compliance right. This is the most expensive mistake. If your plan doesn’t comply with Section 409A, your employees face penalty taxes and you face potential liability. Work with a tax attorney.
Vague trigger events. “When the company is profitable” means different things to different people. Define triggers with specific numbers and timelines.
No cap on the phantom pool. If you keep granting phantom units without a cap, you could owe a massive cash payout that the business can’t afford.
Forgetting about cash flow. Phantom equity is a cash obligation. When the trigger hits, you need the money. If you sell the company, that’s easy: it comes out of the sale proceeds. If it’s a revenue milestone, you need cash on hand.
Using phantom equity when real equity is better. If your team members are true co-founders who are building the company from scratch, phantom equity sends the wrong signal. They want real ownership. Use dynamic equity or actual membership units instead.
Frequently asked questions
What is phantom equity in simple terms?
Phantom equity is a cash bonus plan that’s tied to the value of the company. Employees receive fictional “units” that track the company’s growth. When a trigger event happens (like a sale), they receive a cash payout based on what those units would be worth. They never become actual owners of the company.
Is phantom equity the same as phantom stock?
Yes. Phantom equity, phantom stock, phantom units, and shadow equity all refer to the same concept. The terminology varies by company type: “phantom stock” is more common for corporations, while “phantom equity” or “phantom units” is more common for LLCs and partnerships.
How is phantom equity taxed?
Phantom equity payouts are taxed as ordinary income at the employee’s marginal tax rate. There’s no capital gains treatment available. The company can generally deduct the payout as a compensation expense. The plan must comply with IRC Section 409A to avoid penalty taxes of 20% plus interest.
Can phantom equity be used in an LLC?
Yes, and this is one of its primary use cases. In an LLC taxed as a partnership, giving actual membership units makes someone a partner, which generally changes their tax status from W-2 to K-1 and may give them voting rights. Phantom equity provides the financial upside without any of these complications. The employee stays an employee.
How much phantom equity should I give an employee?
There’s no universal answer, but total phantom equity pools typically range from 10-20% of the company’s value. Individual grants depend on the employee’s role, seniority, and impact on the business. A key executive might receive 3-5%, while a senior employee might receive 1-2%. Use benchmarks from your industry and consider what the cash payout would actually be at various company valuations.
What happens to phantom equity if I leave the company?
It depends on the plan. Typically, unvested phantom units are forfeited upon departure (similar to standard equity vesting). Vested units may be forfeited, retained until a later payout event like a sale, or paid out at departure. Whichever it is, the agreement should fix it in advance. Leaving the choice to the company’s discretion at the time can create Section 409A problems.
Is phantom equity better than real equity?
Neither is universally better. Phantom equity is better when you want to incentivize employees without giving up ownership, voting rights, or changing their tax status. That’s common in LLCs and service businesses. Real equity can be better for ownership alignment, particularly for co-founders and key hires at venture-backed startups, but its tax treatment depends on the instrument and transaction. Consult compensation and tax professionals before choosing a plan.
Phantom equity is a powerful tool for the right situation. If you’re an LLC or service business looking to reward key employees without the complexity of actual ownership, it’s worth exploring with a compensation attorney.
If you’re at an earlier stage and trying to figure out how to split equity fairly among co-founders, that’s a different problem, and dynamic equity is designed to solve it. Try the equity calculator to see what a contribution-based split looks like for your team.
Ready to split equity fairly?
Equity Matrix tracks contributions and calculates ownership automatically.
Get Started FreeThis article is for informational purposes only and does not constitute legal, tax, or financial advice. Equity Matrix is not a law firm, accounting firm, or financial advisor. Consult a qualified professional for guidance specific to your situation.
Co-founder, Equity Matrix
Sebastian writes about startup equity, founder dynamics, and building fair partnerships.
Keep reading
Phantom equity and dynamic equity: how to combine them
Phantom equity is usually a fixed grant. Here's how to make it contribution-based instead, with two structures, a worked example, and the 409A and wage-law limits.
Read more →50/50 partnership deadlock: how to break a tie before it breaks the business
Equal partners with no tie-breaker can stall a business for months. The deadlock clauses that work, how a shotgun clause plays out, and what to do if you're stuck.
Read more →