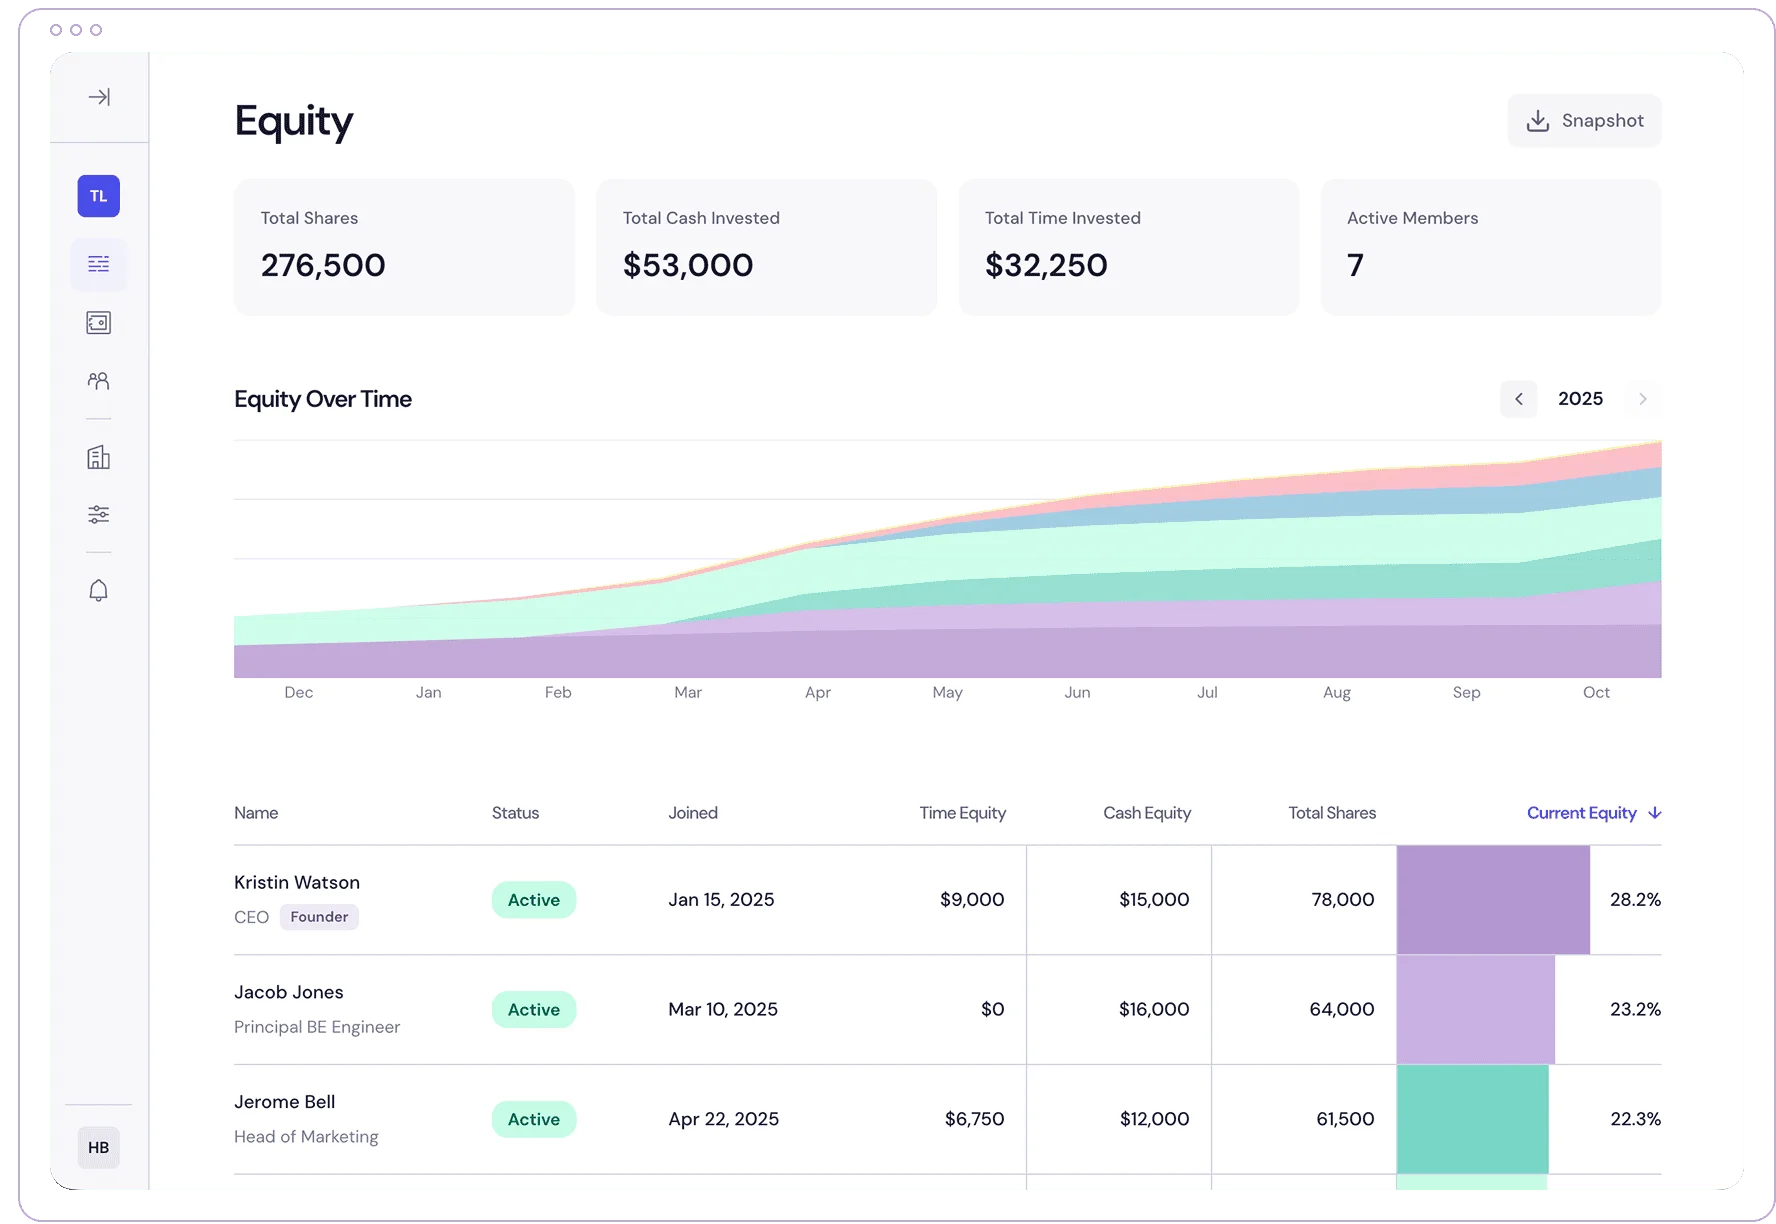
Phantom equity and dynamic equity aren’t competing ideas. Phantom equity answers “what kind of stake does this person hold?” Dynamic equity answers “how big should it be?” You can use one for each question.
A typical phantom equity plan hands someone a fixed number of units on day one. Five percent, vesting over four years. That has the same weakness as a fixed founder split: it’s a guess about future contributions, made before anyone has contributed anything.
An alternative is to let people earn phantom units the same way founders earn real ownership in a dynamic equity model, based on what they actually put in. A business owner I’ve been talking with recently wants exactly this. They have partners who should own the company and key people who shouldn’t, and they want everyone’s stake tied to contribution.
This post covers how that hybrid works, two ways to structure it, and where it runs into legal limits. If phantom equity is new to you, start with our phantom equity explainer first.
Why anyone would want both
Here’s the usual setup. A couple of partners own an LLC. They’ve split ownership based on contributions, or they want to. Then there’s a key person, often an operations lead or a senior tech, who is doing owner-level work.
Both partners want that person to share in the upside. Neither wants to make them a member of the LLC.
Making someone a member changes a lot. In an LLC taxed as a partnership, they generally stop being a W-2 employee and start getting a K-1, and they may owe self-employment tax on their share of profits. Depending on state law and the operating agreement, they may also get voting rights. And unwinding it if they leave is real legal work.
Phantom equity sidesteps most of that. The person stays an employee, and the partners keep control. What a time-vested fixed grant can’t do is adjust. It pays the same whether the person ends up carrying the business or coasting.
How dynamic phantom equity works
Most of the mechanics borrow directly from contribution-based equity.
Contributions get a value under rates everyone agrees on in advance. For the partners, that’s unpaid time at an agreed market rate, cash invested, and other resources. Those contributions determine their real ownership, the way contribution tracking works in any dynamic model.
A key employee’s contributions get valued too, but they earn phantom units instead of real ones. The rest of the phantom plan stays standard: defined payment events, a valuation formula, and a payout in cash.
There’s one important difference for employees. They already get a salary, so you don’t count their full time. You count the gap between their agreed market rate and what you’re actually paying them. If their market rate is $110,000 and they take $80,000 to work for you, the $30,000 a year they’re leaving on the table is what earns phantom units.
Two ways to structure it
Your biggest design decision is whether phantom units share a pie with real ownership or sit in a separate pool.
Option 1: one shared pie
All contributions go into a single pie under the same rates and multipliers. Partners hold their slices as real membership units. The employee’s slices are phantom units, a contractual right to a cash payout equal to their share of the pie.
At a sale, the employee is paid their share in cash, and the partners split what’s left according to their real ownership.
This is the closest version to pure contribution-based fairness. The downside is that the partners can’t cap the cost. If the employee contributes heavily for years, their phantom share can grow larger than anyone planned. The plan document also has to spell out whether phantom slices count when calculating the partners’ voting percentages (usually they shouldn’t).
Option 2: a capped phantom pool
Partners set aside a fixed share of the company’s value for phantom payouts, say 10%. That pool is the most phantom holders can ever receive. Inside the pool, each holder’s share is set by their contributions relative to the other holders.
Meanwhile the partners’ own split stays dynamic among themselves, applied to the other 90%.
This is the version I’d start most businesses with. The partners know the maximum the plan can cost them. Phantom holders still get a stake that reflects what they did relative to each other. And a capped pool is a familiar feature of conventional phantom plans, so the drafting starts from known ground.
Shared pie vs. capped pool
| Factor | One shared pie | Capped phantom pool |
|---|---|---|
| Cost to partners | Open-ended | Capped (e.g. 10% of value) |
| Fairness across everyone | Highest | Fair within each group |
| Predictability | Low | High |
| Best for | A key person who is close to a partner | Several key employees |
| Drafting complexity | Higher | Lower |
A worked example
Here’s how the capped pool version plays out. Two partners own an HVAC company as an LLC. They set aside a 10% phantom pool for two key employees.
Over three years, the employees’ contribution gaps add up like this:
Phantom pool allocation after three years
| Employee | Market rate | Salary paid | Annual gap | Gap over 3 years | Share of pool |
|---|---|---|---|---|---|
| Operations lead | $110,000 | $80,000 | $30,000 | $90,000 | 75% |
| Senior tech | $85,000 | $75,000 | $10,000 | $30,000 | 25% |
Because the operations lead gave up three times as much in pay, they hold three times as much of the pool.
Now the partners sell the business, and the plan defines the payout base as net proceeds to the owners: $3 million. The phantom pool is 10%, or $300,000. The operations lead receives $225,000 and the senior tech receives $75,000, both as cash compensation. The partners split the remaining $2.7 million according to their own dynamic split.
With fixed grants, the partners would have had to pick those percentages three years earlier, before knowing who would give up more pay.
Where the hybrid runs into legal limits
Simple structure, complicated paperwork. A few of these limits can sink a plan written without a lawyer.
Employees still need a real wage
In the US, employees have to receive at least minimum wage, plus any overtime they’re owed, in actual pay. Exempt roles have their own minimum salary rules, and some states set stricter ones. Phantom units can’t stand in for any of that. Counting only the gap above salary is an economic design choice, not a legal safe harbor. The salary itself has to satisfy wage law on its own.
Payment events have to be fixed in advance
Phantom equity that pays out later is usually deferred compensation under IRC Section 409A. Payments can generally only happen on events the rules allow, such as a change in control, separation from service, death, disability, or a specified date or fixed schedule. Each of those has a specific regulatory definition, and they have to be written into the plan up front. A plan that lets the partners decide later when or whether to pay can trigger penalty taxes for the employee.
A dynamic plan adds a real complication: the number of units grows over time, and each new accrual may be treated as its own deferral. A dynamic phantom plan can be structured to comply, but how each accrual is earned, vested, and paid needs careful 409A drafting. The amount can move. The rules for computing and paying it shouldn’t.
Keep the valuation formula separate from the payment events, too. An EBITDA or revenue multiple tells you what units are worth. It isn’t a reason to pay them. A plan that only pays at a sale also needs to say what happens if a sale never comes.
Phantom plans can fall under ERISA
A phantom plan that systematically defers pay to retirement or departure can be treated as a pension plan under ERISA. If the plan is unfunded, maintained mainly to provide deferred compensation, and limited to a select group of management or highly paid employees, it can qualify as a “top hat” plan. That’s still an ERISA plan, but it’s exempt from most of ERISA’s requirements. The company generally files a one-time statement with the Department of Labor within 120 days after the plan becomes subject to ERISA. Some sale-triggered plans fall outside ERISA as bonus arrangements, particularly when payments aren’t systematically deferred until someone leaves, but that depends on the plan’s terms and how it’s run. Ask your lawyer which bucket yours falls in.
Payouts are taxed as wages
When the payout comes, it’s ordinary compensation income for the employee, subject to income tax withholding. FICA timing can differ: for deferred compensation, Social Security and Medicare tax generally applies once the work is done and the units vest, rather than when they’re paid. The company can generally deduct the payout when the employee includes it in income. Partners selling their real ownership may get capital gains treatment instead, so employees should know this going in.
When phantom units are the wrong answer
Sometimes the hybrid is a sign that someone should just be a partner.
If your “key employee” is contributing at the same level as the partners, taking little or no salary, and making decisions alongside them, phantom units can feel like a second-class stake. They’re carrying owner-level risk and getting employee-level treatment. In my experience that tends to come out eventually, often at a bad time.
For an LLC, a profits interest is worth a look in that situation. It gives the person real ownership of future growth. A properly structured profits interest may not be taxed at grant under IRS Revenue Procedure 93-27, though the safe harbor has exceptions and unvested interests need extra care. The tradeoff is that they become a member, with the K-1 and governance implications that come with it.
Partners’ ownership deserves a tax adviser’s look too. Shifting LLC percentages based on contributed work can have partnership tax consequences, and the operating agreement should handle how capital accounts move.
Here’s the rough test I’d use:
Phantom units or real ownership?
| If the person… | Consider |
|---|---|
| Takes a near-market salary and reports to the partners | Phantom units |
| Wants upside but not responsibility for the business | Phantom units |
| Takes little or no salary and makes partner-level decisions | Real ownership (dynamic split or profits interest) |
| Is personally guaranteeing loans or investing cash | Real ownership |
Setting it up
If you’re going to try the hybrid, here’s the order I’d work in.
- Decide who’s a partner and who’s a phantom holder. Use the table above. It’s a judgment call, so make it explicitly.
- Pick shared pie or capped pool. If you’re unsure, start with a capped pool.
- Agree on market rates. Set and document a market rate for every role, partners and employees alike. Our sweat equity valuation guide covers how.
- Define payment events and the valuation method separately. For example, pay at a sale or a fixed date, and value units using a formula like an EBITDA multiple when there’s no sale price to use.
- Decide what happens when someone leaves. Spell out whether unvested phantom units are forfeited, and whether vested ones pay out at departure or wait for a later event. It’s the same conversation you’d have about a co-founder who stops contributing, just with cash instead of ownership.
- Have a compensation attorney write the plan. Bring them the structure. Let them handle 409A, ERISA, and your state’s wage rules.
- Track contributions continuously. A dynamic plan is only as good as its records. If nobody logs contributions as they happen, you’ll be reconstructing three years of history at the worst possible moment.
That last step is the one I see slip most often. Equity Matrix logs and values contributions as they happen, at each person’s rate. The pool cap, phantom terms, vesting, and payouts live in your plan document.
Frequently asked questions
Can you combine phantom equity and dynamic equity?
Yes. Partners can earn real ownership through a dynamic split while key employees earn phantom units through the same contribution-based method. The phantom units pay out in cash at defined events instead of conveying ownership. The combined plan still has to meet the usual phantom equity rules, including Section 409A.
How are phantom units earned in a dynamic plan?
Usually through the gap between an employee’s agreed market rate and the salary they’re actually paid. That gap is valued the same way a partner’s unpaid time would be. The plan document sets how the gap converts to units and when those units vest and pay out.
Does dynamic phantom equity comply with Section 409A?
It can be structured to comply, but it takes careful drafting. The payment events and the formula for calculating units need to be fixed in the plan from the start, and each new accrual may be treated as a separate deferral. A plan where the owners decide later whether or when to pay tends to create 409A problems. Have a compensation attorney review it before anyone earns a unit.
Should phantom units share a pie with the owners?
It depends on how predictable you need the cost to be. A shared pie values every contribution under the same rates but leaves the partners’ cost open-ended. A capped phantom pool, often around 10% of company value, limits what the plan can cost and still allocates by contribution inside the pool. For most businesses, I’d start with the capped pool.
Ready to split equity fairly?
Equity Matrix tracks contributions and calculates ownership automatically.
Get Started FreeThis article is for informational purposes only and does not constitute legal, tax, or financial advice. Equity Matrix is not a law firm, accounting firm, or financial advisor. Consult a qualified professional for guidance specific to your situation.
Co-founder, Equity Matrix
Sebastian writes about startup equity, founder dynamics, and building fair partnerships.
Keep reading
Phantom equity explained: how it works for LLCs
Phantom equity pays like ownership without giving up actual shares. How phantom stock plans work for LLCs and service businesses, tax treatment, and when it beats real equity.
Read more →50/50 partnership deadlock: how to break a tie before it breaks the business
Equal partners with no tie-breaker can stall a business for months. The deadlock clauses that work, how a shotgun clause plays out, and what to do if you're stuck.
Read more →